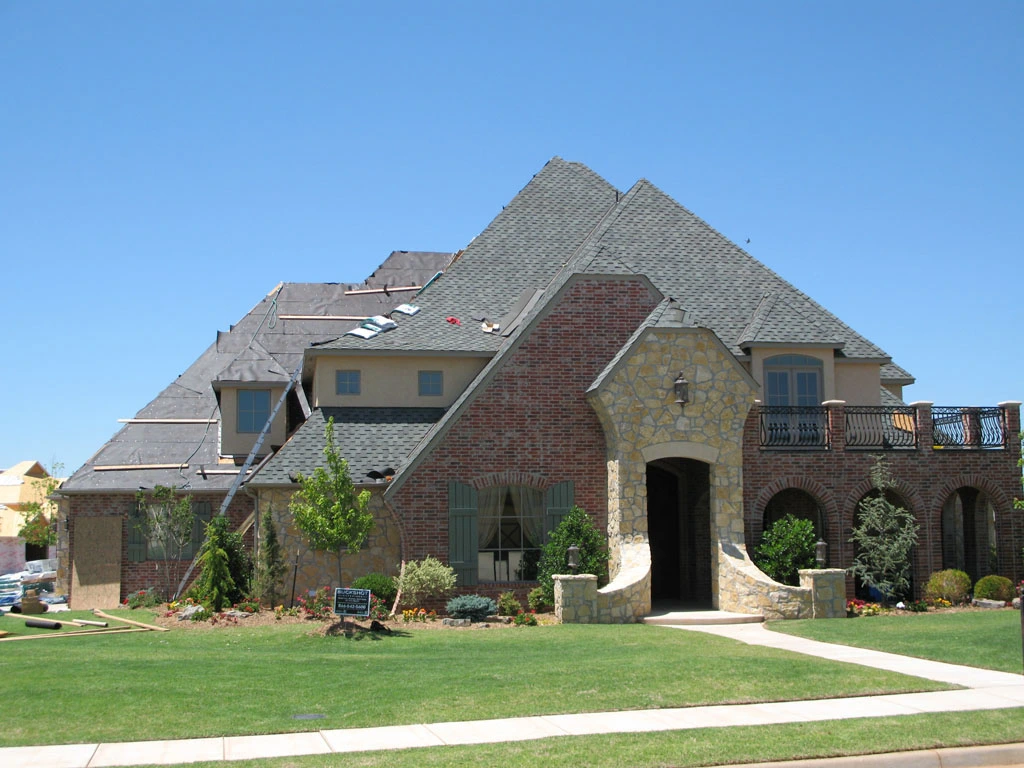
It depends on your policy and your state. Many states have adopted rules requiring a reasonably uniform appearance when replaced items do not match, but the wording differs and some policies limit matching. Ask your state insurance department what applies, and read your policy for matching language or a matching limitation endorsement.
Get My Free Estimate →- Why matching is the real issue in a siding claim
- What decides whether insurance replaces all of it
- What courts have said about siding matching
- How to show the new siding won't match
- What a siding settlement usually looks like
- If the insurer will only pay for one wall
- Check the hail damage first
- Getting help with a siding claim
- FAQs
Sometimes. Whether insurance replaces all of your siding, or only the damaged wall, depends on your policy wording, your state's claim rules, and whether siding that matches the rest of the house is still available.
Insurers agree they owe a repair that restores your home to its condition before the storm. The argument is over how much siding has to come off to do that, and the homeowner usually has to show that a partial repair will not match.
Why matching is the real issue in a siding claim
Matching becomes a problem because siding changes after it goes up. Colors are discontinued, profiles and panel widths change, and siding on the sunny sides of a house fades over the years.
A new panel set into a faded wall can stand out even when it is the same product. When the original line is no longer made, the replacement may not lock into the old panels at all.
That is why a claim for a few cracked panels on one wall can turn into a question about every wall of the house.
What decides whether insurance replaces all of it
Four things usually settle the question, and the first two set the rules for the other two.
Your policy wording. Look for words like "matching," "uniform appearance" or "like kind and quality," and check for an endorsement that limits matching. Some insurers have added language that caps payment to the damaged area only.
Your state's claim rules. Many states have adopted a version of a model regulation that requires the insurer to replace items in the area so the result has a reasonably uniform appearance. States word it differently, so ask the Wisconsin Office of the Commissioner of Insurance or the Iowa Insurance Division what applies to your policy.
Whether matching siding still exists. If the exact product, profile and color are still made, the insurer will usually price replacing only the damaged pieces. If they are discontinued, you have a much stronger case for more.
Where the area ends. Adjusters often agree to replace a whole wall but stop at the corners. Disputes usually turn on whether a mismatched wall that you can see from the same spot as the others is still a reasonable repair.
What courts have said about siding matching
Courts have gone both ways, because each case turns on the policy language and the state. In 2019 a federal appeals court ruled that an insurer had to pay to replace the siding on every side of hail-damaged condominium buildings in Illinois. The court found that mismatched siding would not return the buildings to their condition before the storm.
Other insurers have won cases where their policy clearly limited payment to the damaged area. Treat court rulings as a sign of what is arguable, then read your own policy.
How to show the new siding won't match
The burden of proof usually sits with you or your contractor, so build the evidence before the adjuster decides. These steps cover what an adjuster looks for.
- Identify the siding. Note the manufacturer if you know it, the profile, the exposure (the visible height of each course) and the color name.
- Pull a sample. A contractor can remove a damaged piece from an inconspicuous spot so it can be compared with what is available today.
- Get it in writing from a supplier. A letter or email stating that the product or color is discontinued is strong evidence.
- Photograph the difference. Hold a new panel against the wall in daylight and photograph it next to the faded siding on more than one side.
- Ask the adjuster in writing. Ask whether a matching product exists, and if so, ask for its name so you can confirm it actually fits and matches.
Adjusters often order a material-identification report on a siding sample. Ask for a copy, because it often settles whether a match exists.
Want this documented properly the first time? Call (608) 909-9109 for a free on-site inspection, and we will meet your adjuster on site.
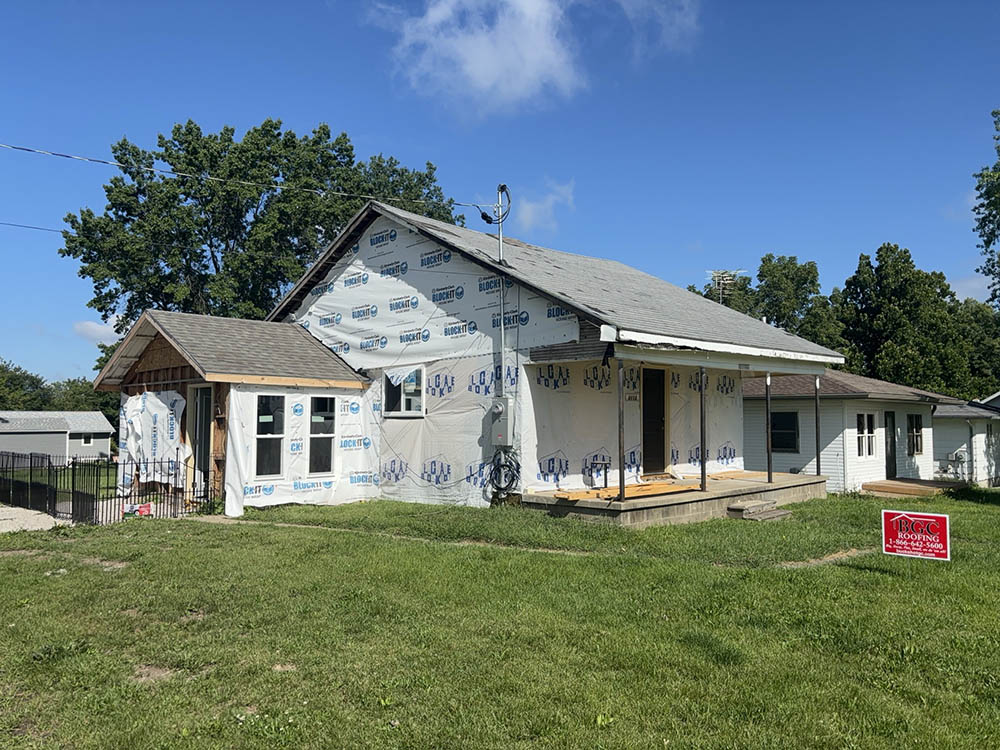
What a siding settlement usually looks like
Your deductible applies once per claim, whether the insurer pays for one wall or the whole house. Check whether you carry a percentage wind and hail deductible, because that can be larger than a flat one.
Many policies pay in two parts. The first check covers the depreciated value, and the rest is released after the work is finished, which our guide to reading your insurance estimate explains line by line.
If matching turns out to be impossible after the work starts, your contractor can request more through a supplement. Our guide to roof insurance supplements covers how that works, and siding follows the same process.
If you want a different siding product than the one you had, you can usually upgrade by paying the difference. Tell your insurer and your contractor before work begins so the paperwork reflects it.
Want a straight answer on your roof?
We'll inspect it, document everything, and tell you honestly what you're looking at, even if the answer is patch it for now. No pressure.
If the insurer will only pay for one wall
Start by asking for the decision in writing, with the policy provision the insurer is relying on. A written answer tells you whether the dispute is about coverage or about the amount.
Then add evidence and ask for a reinspection, using the supplier letter, the sample and the side-by-side photos. If the disagreement is only about the dollar amount, most policies include an appraisal clause that lets each side hire an appraiser and use a neutral umpire.
If you still disagree, you can file a complaint with your state insurance department at no cost. Our guide to what to do when a claim is denied walks through each step, and the same path applies to siding.
Check the hail damage first
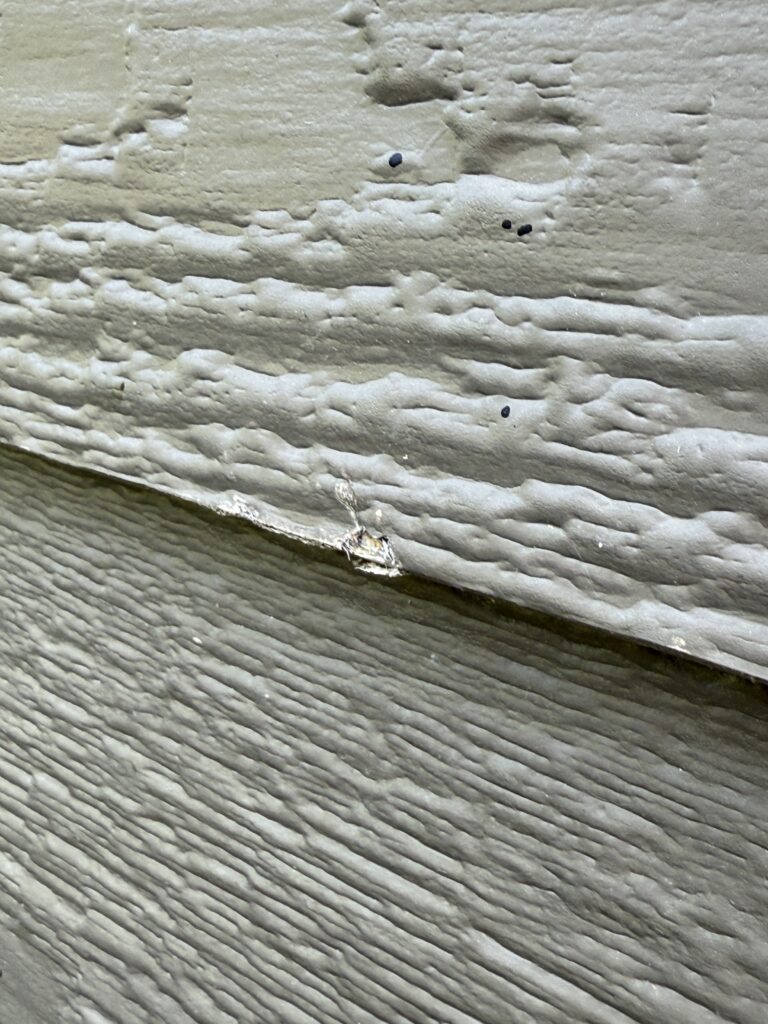
Matching only matters once the damage itself is documented. Hail tends to crack, chip and puncture vinyl rather than dent it, and the damage is easiest to see in low, angled light.
Our guide to hail damage on siding shows what to look for on each siding type, and our guide to storm damage on siding covers wind damage as well.
Getting help with a siding claim
A siding claim goes better when the damage, the product and the mismatch are documented before the adjuster writes the estimate. Buckshot Exteriors is family-owned and has worked on exteriors since 1979, with offices in Madison, WI and Centerville, IA.
We offer a free on-site inspection and meet your insurance adjuster on site to document hail and wind damage. Our storm-damaged siding page explains the repair side, our insurance claims page explains the process, and our siding replacement page covers what a full replacement involves.
Call (608) 909-9109 to schedule a free inspection. If a storm just came through, our 24-hour storm line is the same number.
Get a straight answer on your Madison roof
Wisconsin storm season and insurance non-renewal letters do not wait. Get a free, no-obligation inspection and an honest assessment of exactly what your roof needs, even if the answer is to wait.