Get a free contractor inspection first. A contractor inspection is not reported to anyone, so nothing lands on your loss history, and you find out whether you have documentable hail damage before a claim is opened. A filed claim does go on your CLUE loss-history report, typically for about five to seven years.
Get My Free Estimate →- What a professional hail damage roof inspection actually involves
- Why you want a contractor on the roof before the adjuster
- "My insurance company wants me to use their contractor"
- What it actually costs you out of pocket
- How the money actually reaches you (and why your lender is on the check)
- What you can safely check yourself, from the ground
- What real hail damage looks like on a roof
- If your claim gets denied or underpaid
- How to spot a storm chaser before you sign
- Permits, code, and timing after approval
- Get your free hail damage roof inspection in Madison
- FAQs
If hail just worked through your neighborhood, do this first: get a free hail damage roof inspection from a local contractor before you call your insurance company. You want to know whether you have documentable damage, and you want your own photos, before a claim is opened and an adjuster makes the call.
Short answer, if you only read this much:
- Stay off the roof. Photograph dented gutters, screens, and your A/C unit from the ground.
- Write down the storm date and rough time.
- Book a free contractor inspection. It is not reported to anyone and does not touch your loss history.
- Only then decide whether to file, and ask your contractor to meet the adjuster on the roof.
- Check your declarations page for a separate wind/hail deductible before you file.
You can request a free inspection here or call the number at the top of this page.
Wisconsin's hail season runs roughly from spring into late summer, and it is wildly uneven. One cell can hammer a block in Sun Prairie, Verona, Stoughton, or Madison's west side and leave a street a mile away untouched. That is why "my neighbor got a new roof" and "it looks fine from the driveway" are both unreliable.
Hail damage is usually quiet. It does not punch holes. It fractures the shingle mat and strips the granules that shield the asphalt from UV. Our hail damage repair page covers what the repair itself typically involves once damage is confirmed.
What a professional hail damage roof inspection actually involves
A real hail damage roof inspection is a systematic, slope-by-slope exam of the roof and the soft metals around it, and it takes about 45 to 90 minutes on a typical Madison home. It is not a glance from the lawn.
1. Ground and soft-metal check. Hail marks soft aluminum before it marks shingles. We look at gutters, downspouts, gutter aprons, fascia wraps, roof vents, turbine caps, A/C condenser fins, and window screens. Those dents tell us hail size and direction.
2. Directional read. Hail rides the wind, so damage concentrates on one or two slopes. We check every slope, including the ones you cannot see from the street.
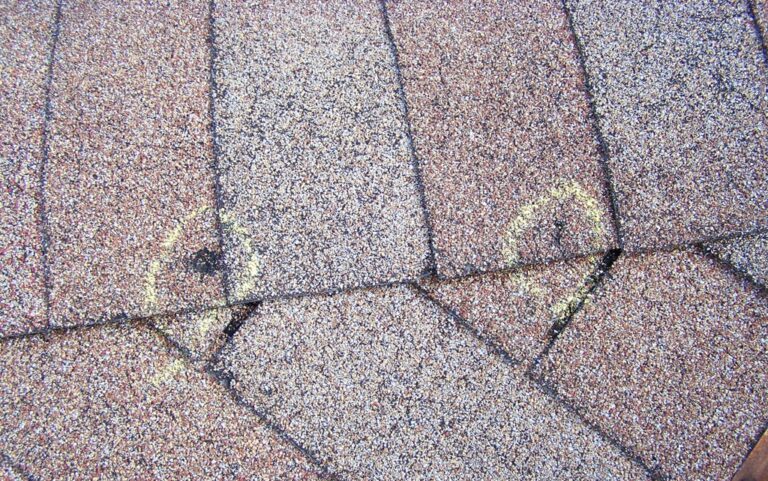
3. Test squares. We chalk a 10 ft by 10 ft square on each slope and count verified impacts inside it. This is the same method adjusters use. In our experience, roughly 8 verified impacts in that square is a common rule of thumb for calling a slope damaged, but several carriers publish no fixed number at all and the call varies by adjuster. The count and the photos are what carry the claim.
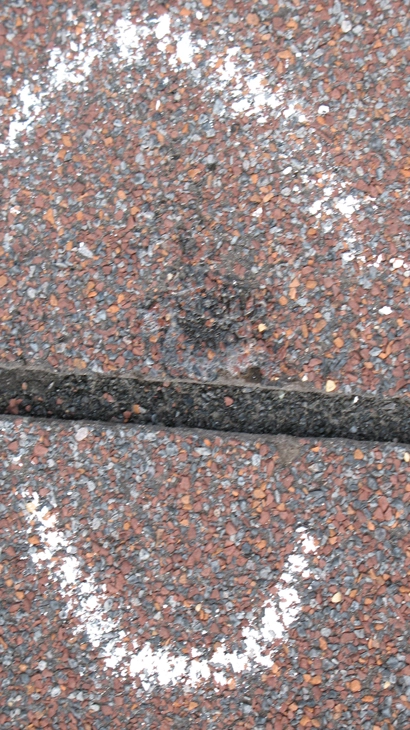
4. Shingle-by-shingle verification. Real hail bruising is soft, round, granules gone, mat fractured underneath. We separate that from blistering, foot traffic, mechanical scuffs, and ordinary age. Guessing wrong here is how claims get denied.
5. Leak-prone details. Ridge and hip caps, valleys, step and counter flashing, chimney saddles, skylight seals, and rubber pipe boots. Cracked boots are a classic delayed leak and one of the most commonly missed items on a fast adjuster walk.
6. Attic and decking, when you want it. Daylight at penetrations, moisture staining on sheathing, rusted nail shanks, wet insulation, and whether the roof is ventilated well enough.
7. The rest of the exterior. Siding, window wraps, trim, garage doors, deck rails. Much of it can fall under the same claim.
Can your inspector's own footsteps mark my roof?
Fair question, and it is the reason we warn you off the roof. Done correctly, no: we photograph each slope before we walk it so there is a time-stamped baseline, we step on the full shingle courses rather than the edges, we avoid walking hot shingles in midday heat when the asphalt is soft, and the chalk we use for test squares washes off in the first rain. An inspector scuffing granules loose with careless boots is a real failure mode, which is why you want someone who inspects roofs for a living rather than a seasonal crew.
What you get afterward
We walk you through the photos on a tablet before we leave, then send a written report with slope-by-slope photos, impact counts per test square, photos of dented gutters and vents and flashings, the documented storm date, measurements, pitch, layer count, and a straight repair-or-replace recommendation with a line-item scope. It is formatted so an adjuster can follow it.
If we do not find storm damage, the report says exactly that, and you have not spent a dollar or opened a claim you did not need.
Ask who is coming out. Buckshot General Contracting has been family-owned since 1979, we give you the inspector's name when we schedule, and our Wisconsin DSPS dwelling contractor credentials are yours to verify on the state license lookup. You can also look through recent projects around Dane County to see the work before you call.
Why you want a contractor on the roof before the adjuster
Adjusters move fast after a hail event, and they are not your advocate. Most are carrying a heavy storm load, spend a limited window per house, and are trained to be conservative on marginal slopes. Nobody is going to hunt for your cracked pipe boot on your behalf.
Inspecting first changes three things:
- Nothing is on your record yet. A free contractor inspection is not reported anywhere, no claim file, no CLUE entry. A filed claim does go on your loss history, usually five to seven years. Some carriers log a "would this be covered?" phone call as an inquiry, so if you call to ask a question, say plainly that you are asking, not filing, and ask whether it gets logged.
- You start from evidence. Impact counts, photos, and a scope already exist.
- We meet your adjuster on-site. Walking the roof together settles more disagreements than any phone call afterward. We have been doing it in south-central Wisconsin as a hail and storm damage contractor for decades, including on plenty of roofs where something got missed the first time.
One more thing homeowners worry about: hail is a weather loss, not an at-fault loss, so a single documented claim is not the same as a liability claim on your record. What tends to change rates in our area is region-wide repricing after bad hail years. Ask your agent directly before you file.
Storm just hit? Get on the schedule for a free, no-pressure inspection. Call the number at the top of this page or request a visit online. After severe weather we dispatch emergency tarping around the clock; routine inspections get booked during business hours.
"My insurance company wants me to use their contractor"
You choose who works on your house. A carrier can recommend a managed-repair or preferred-vendor program, and some of those contractors do fine work, but the carrier cannot make program participation a condition of paying a covered loss.
If an adjuster steers you, do three things. Ask politely for that requirement in writing. Check your own policy language, because it will talk about paying for covered damage, not about who installs it. Then tell them you have a licensed, insured local contractor and ask them to coordinate the inspection with us.
Keep in mind a program contractor is paid by the carrier and works to the carrier's pricing. That is not automatically bad, but nobody in that arrangement is being paid to argue for a wider scope on your behalf.
What it actually costs you out of pocket
Your out-of-pocket on an approved hail claim is normally your deductible plus any upgrades you choose. Pull your declarations page before you file, because two things surprise Madison homeowners constantly.
Percentage wind/hail deductibles
A flat deductible is commonly $1,000-$2,500. But we regularly see Dane County policies with a separate wind/hail deductible written as a percentage of dwelling coverage, often 1%-2%. On a $400,000 dwelling, 1% means $4,000 out of pocket. Know that number before you decide.
What if you cannot cover the deductible?
Say so at the inspection, because there are honest ways to handle it. The deductible can often be split across the two insurance payments, since the initial check and the depreciation release arrive weeks apart. We can set you up with third-party financing. Or we phase the scope so the roof goes on now and approved gutter or siding items follow on their own timeline.
What we will not do is waive it or "eat" it. If the carrier is billed for money you never paid, that is misrepresentation to your insurer, and it can void your claim and expose both of us under Wisconsin insurance fraud law. Any contractor who offers it casually is telling you how they handle everything else.
ACV vs RCV, and roof depreciation
Insurance does not automatically buy you a brand-new roof.
- RCV (replacement cost value) policies pay the depreciated amount first, then release the held-back depreciation after the work is finished and invoiced. That is normal, not a scam.
- ACV (actual cash value) policies pay depreciated value only. On an older roof, that gap can run into thousands.
- We also see roof surfaces payment schedules on some policies locally, which depreciate older roofs steeply by age, plus cosmetic damage exclusions that pay for leaks but not dents on metal roofs and soft metals.
Bring the wind/hail endorsement to the inspection and we will read it with you.
How the money actually reaches you (and why your lender is on the check)
If you have a mortgage, expect your servicer's name on the claim check. Your lender holds a financial interest in the house, so once the payment passes their threshold the carrier typically issues it to you and the servicer jointly.
Here is the sequence:
- You endorse the check and send it to the servicer's loss-draft department, usually with a signed contract, the adjuster's loss report, and a W-9 from your contractor.
- The servicer deposits it into escrow.
- Funds are released in draws, commonly an initial advance, a draw at about halfway, and the balance at completion, often after an inspection or a signed completion certificate.
- Each draw commonly takes one to three weeks to process.
Start that paperwork the day the check arrives, not the week before the crew shows up. Lender delays, not roofing crews, are the most common reason a Madison hail job stalls.
A related question we get: can you pocket what is left over, or skip part of the approved scope? Realistically, no. The depreciation holdback is only released for work completed and invoiced, so skipping items means losing that money, and billing for work nobody did is fraud. If a line item truly is not needed, the clean move is to document why and submit a revised invoice. With escrowed funds, the servicer will want any surplus accounted for before closing the file.
What you can safely check yourself, from the ground
Document what you can see without leaving the ground. Wet shingles are genuinely dangerous, and walking fresh hail can create marks that muddy your claim.
Safety first: do not set a ladder on soft ground or wet grass after a storm, do not go up alone, and stay well clear of any downed or sagging power line, tree limb on a service drop, or dangling wire. Call the utility, not us, for anything energized.
From the driveway, aluminum is your best hail gauge. Walk the gutters and downspouts looking for fresh dents, check window and door screens for pockmarks or tears, and look over fascia, soffits, trim, and deck rails for chips and dings. A flattened A/C condenser with bent coil fins means significant stone size. Dents on a car parked outside tell the same story, and a pile of loose granules at the base of a downspout is worth a photo too.
Photograph everything, note the date and rough time, and save it. Insurers verify storm dates against third-party weather data, so your own timeline helps.
Want a straight answer on your roof?
We'll inspect it, document everything, and tell you honestly what you're looking at, even if the answer is patch it for now. No pressure.
What real hail damage looks like on a roof
Asphalt shingles
A round, dark bruise where granules were knocked loose. Press gently and it feels soft, like a bruised apple, because the fiberglass mat underneath is fractured.
One isolated bruise does not guarantee a leak. A slope with repeated bruising is a different story: the exposed asphalt dries out and cracks, and over a few Wisconsin freeze-thaw cycles that slope loses its waterproofing. Plenty of February leaks we chase started with a hailstorm nobody filed on.
Metal flashing, vents, ridge caps
Small round dents, clear and photographable, and the evidence adjusters accept most readily.
Pipe boots and skylight seals
Impact cracks the rubber. Those leaks show up months later, long after anyone connects them to hail.
"My roof is only 8 years old, it can't be damaged"
Age is not armor. A 1.5-inch stone does not care that your shingles are newer. Premium SBS-modified and Class 4 impact-rated shingles hold up noticeably better, but standard laminated shingles bruise at eight years the same as at eighteen. The upside on a newer roof is less depreciation, so the payout is usually better. On a 20-year-old roof with brittle shingles, hail often cracks them outright and the whole slope goes.
"The last guy said I needed a roof and I didn't"
Fair. Ask any inspector for chalked test-square photos with the slope identified, the impact count per square, and the hail size reported near your address. Corroboration matters: if the gutters, vents, and screens are dinged, the shingles almost certainly took hits too. If someone cannot show you that, get a second opinion. We would rather lose a job than put a roof on a house that did not need one.
If your claim gets denied or underpaid
A denial is not the end of it. In order:
- Ask for the adjuster's report and the reason in writing.
- Request a reinspection with your contractor on the roof at the same time.
- Submit a supplement with photos and documentation for missed items (ridge cap, drip edge, flashing, code-required ice barrier).
- Ask your carrier about the appraisal clause in your policy, an independent process for valuation disputes.
- If you are stonewalled, file a complaint with the Wisconsin Office of the Commissioner of Insurance.
Most reversals we see come from better evidence, not louder arguments.
How to spot a storm chaser before you sign
After significant hail around Dane County, out-of-area crews work the neighborhoods, sometimes the same afternoon. The tells are consistent: no permanent local address you could drive to, no verifiable local references, heavy pressure to sign a contingency agreement on the first visit, a vague scope with no line items, and no named warranty holder. If the conversation starts with waiving your deductible, end it there.
Then ask for the paperwork that proves a company is real. Wisconsin DSPS dwelling contractor and qualifier credentials, a current certificate of general liability and workers' compensation insurance, and manufacturer certification such as GAF Master Elite status. We hand ours over without being asked twice.
Get both warranties in writing too: the manufacturer's shingle warranty, including whether a certified installer unlocks enhanced coverage, and the contractor's workmanship warranty with the term spelled out in the contract. A warranty from a company that leaves the state in October is worth nothing.
Permits, code, and timing after approval
In Madison, a residential reroof requires a building permit through the city's building inspection division, and your licensed contractor should pull it, not you. Fitchburg, Sun Prairie, Middleton, and the Dane County towns each run their own process. We pull the permit and handle the inspection.
Two Wisconsin code points matter on a hail rebuild. The Uniform Dwelling Code limits how many layers of roof covering can stay on, so a third layer means full tear-off, and ice barrier membrane is required at the eaves. That eave detail is not red tape here. It is what keeps ice dams from pushing water back into your soffits in January.
On timing, after approval scheduling usually runs a few weeks depending on season and material availability, and a typical roof replacement in Madison is a one or two day tear-off and install. If there is an active leak, we tarp first and worry about paperwork second.
Also know the real deadline: most policies require prompt notice of a loss and then cap how long you have, commonly one to two years from the date of loss. Your policy's "Duties After Loss" and "Suit Against Us" sections spell it out. That is a contract term, not a sales line.

Get your free hail damage roof inspection in Madison
You do not have to sort this out alone. Call Buckshot Exteriors and we will come out, do the full inspection described above, hand you a photo-documented report, and tell you honestly what we find, including "your roof is fine" when that is the answer.
It costs nothing to find out, nothing goes on your insurance record from a contractor inspection, and nobody is going to lean on you to sign. If there is damage, we will explain your deductible and how your carrier pays, walk you through the lender escrow paperwork, meet your adjuster on-site, and do the work with our own crews.
Family-owned and working in south-central Wisconsin since 1979. Call the number at the top of this page or request your free hail damage roof inspection online, and if water is coming in tonight, tell us when you call so we can get a tarp on it.
Get a straight answer on your Madison roof
Wisconsin storm season and insurance non-renewal letters do not wait. Get a free, no-obligation inspection and an honest assessment of exactly what your roof needs, even if the answer is to wait.